Click here to get this post in PDF
Running a small company often means the boundary between work money and home money is paper thin. The owner who answers the phones, approves payroll and chases invoices is frequently the main earner for the family as well. When that person is suddenly injured, the business and the household feel the shock in the same week. Very few budgets on either side are built for that kind of double blow. Even a short absence can reveal how much of a company rests on one set of shoulders.
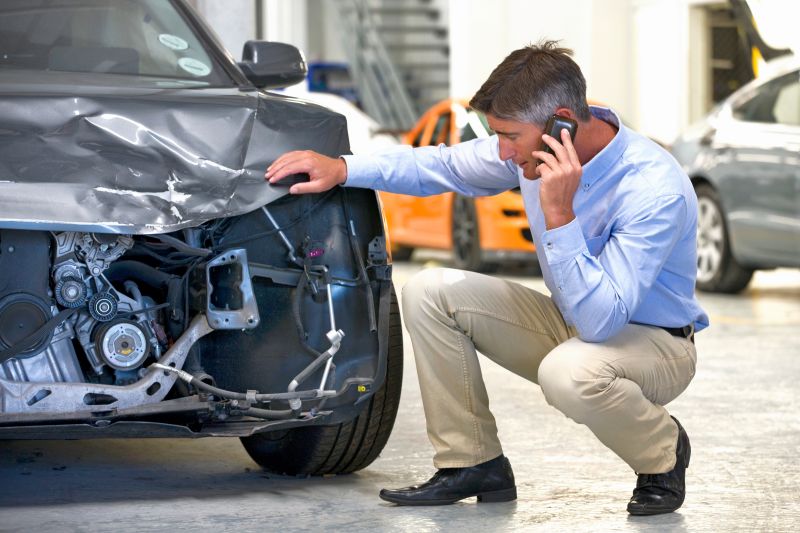
A road collision is one of the most common ways this scenario unfolds. A single afternoon can produce hospital bills, a wrecked vehicle, cancelled meetings and an insurance process that crawls along far slower than any owner would like. The costs rarely end at the body shop, and many of them surface weeks or months after the crash. This piece looks at those ripple effects through a business lens, covering the obvious expenses, the hidden losses and the practical moves that help an owner protect income, credit and the company itself.
Lost Income, Insurance and Getting the Right Advice
Lost earnings are often the largest cost of a crash, and they are the hardest to pin down for someone who works for themselves. As explained by Knight Law Firm, a car accident lawyer can help an injured person see that a claim may reach beyond medical bills and vehicle damage when the injury keeps them from working. A salaried employee can point to a pay stub, while an owner may need tax returns, profit and loss statements and client records to show what was really lost. Missed contracts, delayed projects and customers who switched to a competitor all count, yet they rarely appear on one tidy document. Calendars, emails and invoices showing cancelled work help fill in that picture.
Oklahoma follows a fault-based insurance system, so the at-fault driver’s insurer is usually responsible for the injured person’s losses, up to the limits of the policy. Those limits can be modest compared with the true cost of a serious injury to someone whose income depends on their own labor. Oklahoma also generally allows two years to file a personal injury lawsuit, a window that can slip by while an owner is focused on recovery and keeping the doors open. Accepting a quick settlement before the full cost of treatment is known can be a costly mistake. Once a release is signed, reopening the claim for expenses discovered later is usually not possible.
The Bills That Show Up First
Some costs land on the kitchen table almost immediately. An ambulance ride, an emergency room visit, imaging and a string of follow-up appointments can run up a large balance, and plans with a high deductible leave the patient paying most of it at first. The vehicle brings its own invoices, from towing and storage to repairs or a replacement, plus a rental that an insurer may only partly reimburse. When the damaged car or van was the one used for deliveries and site visits, the company has to find and pay for a stand-in as well. None of these charges wait politely for a claim to be resolved.
Ownership of the vehicle adds another wrinkle. A family car used now and then for company errands may sit under a personal policy that handles business driving differently than the owner assumed. A commercial policy, on the other hand, may set its own conditions about who may drive and for what reason. Sitting down with an agent to read both policies, ideally before anything goes wrong, clears up those questions while the stakes are low. The same conversation is a good moment to ask whether employees driving their own cars on company business are covered.
Daily Commutes and Everyday Exposure
Few owners think of the daily drive as a business risk, yet it may be the most dangerous part of their working day. Commuters in Tulsa who rely on the Broken Arrow Expressway or Interstate 44 at rush hour know the pattern of packed lanes, abrupt braking and drivers glancing at their phones. A merge taken a little too fast or a car stopping short ahead can turn an ordinary morning into a claim file. Experience behind the wheel helps, but it cannot control what everyone else on the road is doing.
Employees face the same exposure when they drive for the business. A delivery driver, a sales representative visiting clients or an office manager running to the bank all add miles on busy roads. When one of them is hurt, the company may lose a key worker and face questions about insurance at the same time. Clear policies about phone use while driving, regular vehicle maintenance and realistic schedules that do not push people to rush all reduce that risk.
Cash Flow, Credit and Keeping the Team Steady
Recovery has a way of pinching the bank balance from two sides. Sales slow when the owner cannot visit clients or finish projects, yet the mortgage, the car payment and the utility bills keep arriving on time. Plenty of owners bridge the gap with a business credit card or the family savings account, and that borrowing can outlast the injury by years. Logging each dollar used to cover the shortfall makes it easier to show how the crash hit the household. Keeping that log apart from routine company spending also spares everyone confusion at tax time.
Staff feel the effects as well. A team that relied on the owner for decisions may stall, and bringing in temporary help adds expense at a difficult moment. Projects that need the owner’s signature or expertise can sit untouched for weeks. Honest conversations with lenders, vendors and employees make a real difference, since many suppliers will adjust payment terms and banks may offer short-term relief to a loyal customer who explains the situation early.
Building a Cushion Before the Next Emergency
Preparation does its best work during the quiet months when nothing is going wrong. An annual look at auto, disability and business interruption policies gives an owner time to close holes in coverage before they matter. A reserve fund holding a few months of household and company expenses buys breathing room if earnings stop without warning. Adding a small amount each month usually feels more realistic than trying to set aside a large sum in one go. Even a partial cushion can stop a short recovery from snowballing into lasting debt.
Spreading knowledge across the team protects the company in a similar way. When more than one person understands invoicing, scheduling and client updates, work can continue while the owner is out of action. Giving a trusted bookkeeper or partner access to the essential accounts helps avoid missed payments and the penalties that follow. Written procedures for the jobs only the owner usually handles turn a crisis into an inconvenience. Those habits serve a business well through any disruption, and they tend to make ordinary weeks run more smoothly too.
Image source: elements.envato.com